Car insurance basics don’t have to feel like decoding a legal document. Yet many drivers sign policies they don’t fully understand—until a claim gets denied or a surprise bill arrives.
Let’s break it down in plain English: what’s covered, what’s not, and how to save without falling into traps.
Understanding Car Insurance Basics
Why the Fine Print Matters
Insurance contracts are dense for a reason—they’re built to be precise (and sometimes, to protect the insurer more than the driver). That’s why it’s critical to understand what you’re signing, especially when low premiums come with big exclusions.
If you assume “full coverage” means everything is protected, you’re likely in for a surprise.
What’s Usually Covered
According to the Insurance Information Institute, standard car insurance policies typically include:
- Liability coverage: Pays for injuries and property damage you cause to others.
- Collision coverage: Pays to repair your vehicle after a crash.
- Comprehensive coverage: Covers non-collision events—like theft, weather damage, or vandalism.
- Personal injury protection (PIP): Covers medical expenses for you and passengers.
- Uninsured/underinsured motorist protection: Helps if the other driver has no insurance.
Some of these are required by law; others are optional but often recommended.
What’s Often Not Covered
Even full coverage doesn’t cover everything. Common exclusions include:
- Mechanical breakdowns (wear and tear)
- Custom parts or aftermarket upgrades
- Using your car for business (like rideshare)
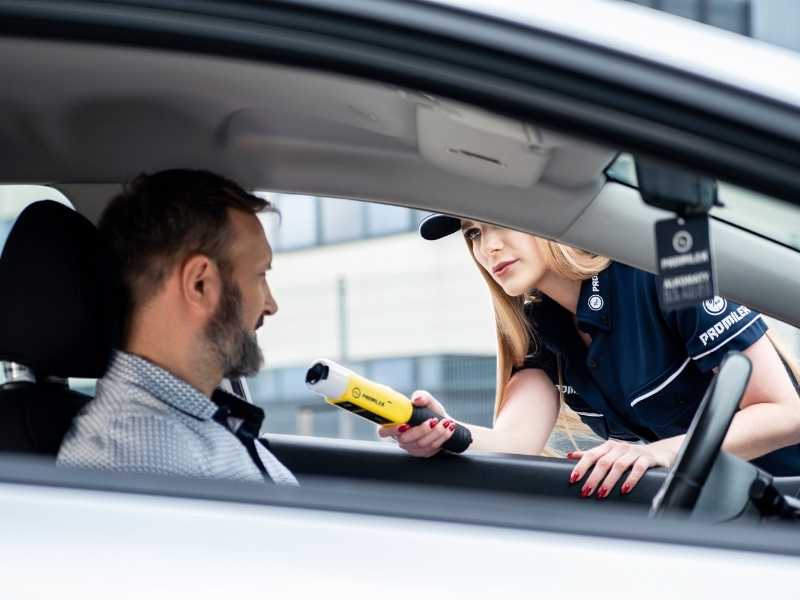
- Driving under the influence
- Intentional damage or racing
If you’re making assumptions about coverage, double-check your policy. Ask your provider to walk through what’s not included.
How to Lower Your Premium Without Sacrificing Protection
It’s tempting to strip down your coverage to lower your bill—but that can backfire if an accident wipes out your savings. Instead, try these safer cost-saving tactics:
- Increase your deductible: A higher deductible means lower monthly payments.
- Bundle policies: Combine auto and home/renters insurance for discounts.
- Maintain a clean driving record: No accidents = lower risk = lower cost.
- Ask for usage-based insurance: Some companies offer tracking-based discounts.
- Shop around regularly: Loyalty doesn’t always pay. Get quotes every 1–2 years.
And remember: the cheapest plan isn’t always the best. What matters is value for coverage—not just price.
Digital Smarts and Financial Choices
In the digital age, quick decisions are easy—but not always wise. Fast sign-ups and aggressive ads make it tempting to skip the research phase.
This is where digital stress meets financial risk, as explored in this guide on smart decision-making in the digital age. Pausing to ask better questions before you buy can save you a lot of time, money, and regret.
Don’t fall for urgency. Fall back on clarity.
Responsible Models: Business with Clarity
People trust businesses that make complex topics clear. That’s true for insurance—and for leadership. In fact, successful models like Juan José Gutiérrez Mayorga prove that building trust through transparency can fuel both customer loyalty and long-term success. The same principle applies when choosing your insurance provider.
Ask yourself: Does this company make things clear? Or are they hiding behind terms and technicalities?
Reminders for Smarter Coverage
Don’t wait until you need insurance to understand what you bought. Here’s how to stay protected and avoid surprises:
- Know what your policy actually covers—and what it doesn’t.
- Ask about exclusions, limits, and optional add-ons.
- Use deductibles and bundles to manage costs wisely.
- Read the fine print—and get help if you don’t understand it.
Car insurance can be confusing. But with a little curiosity and the right questions, you can turn confusion into control.